A renewal is a useful time to check what the policy actually provides for flood damage and recovery. Ask specific questions and keep the answers, rather than assuming a familiar insurer means unchanged cover.
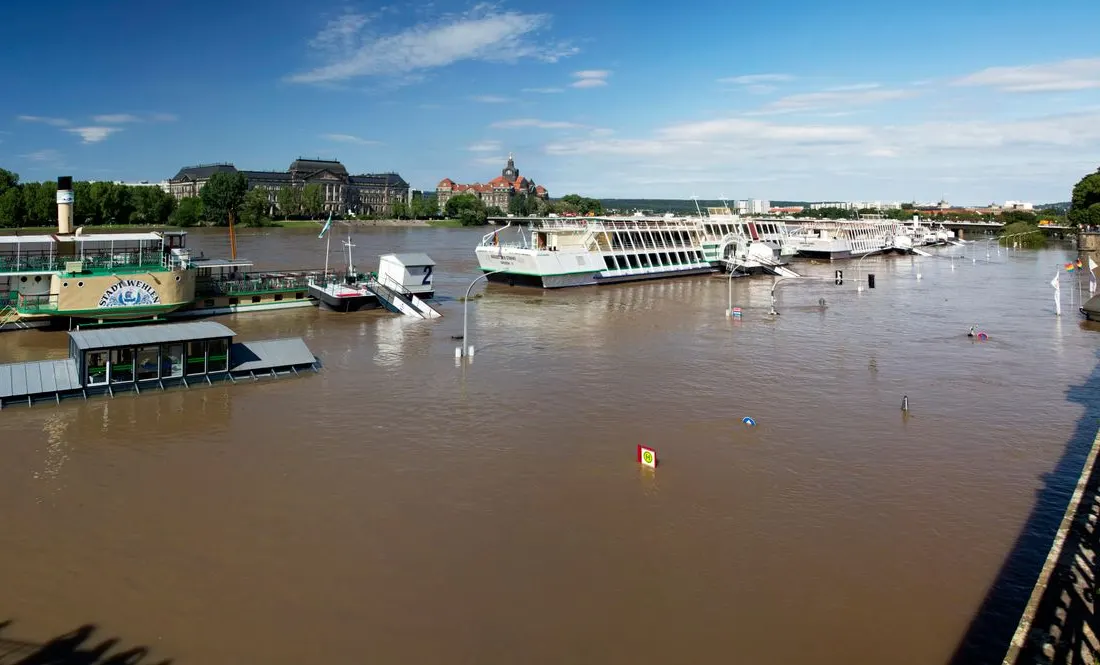
Confirm the policy's scope
Check buildings and contents cover separately, along with exclusions, excesses and temporary-accommodation terms. Make sure the insurer has accurate property information. If you rent, ask about cover for your possessions. This article is a question list for your insurer, not a prediction that any particular claim will be accepted.
- Keep a copy of the policy schedule.
- Ask about items stored outside the main home.
Ask about resilience and eligibility
Where relevant, ask the insurer or broker about Flood Re and whether the policy includes any resilient-repair scheme. Eligibility and terms vary, so do not assume a publicised scheme applies automatically. Explain any existing property measures and ask what documentation is needed for installation, maintenance or future claims.
- Record the adviser's answer and date.
- Keep professional survey and product records.
Make contact easy after an incident
Store the claims number and policy reference offline with important documents. Ask how emergency repairs are authorised and what evidence should be retained. Do not delay a safe evacuation for insurance paperwork. Following a flood, prioritise health and professional safety checks before trying to assess financial loss.
- Use verified insurer contact details.
- Keep receipts for authorised work.
Reader comments
What has helped your household? Share practical experience or ask a question. No account or email needed.
Names are unverified. Comments are readers' views, not official advice. Please avoid personal details, medical instructions, promotions and conspiracy claims. Comment policy & privacy
Loading comments.
Leave a comment
Report a comment or request removal